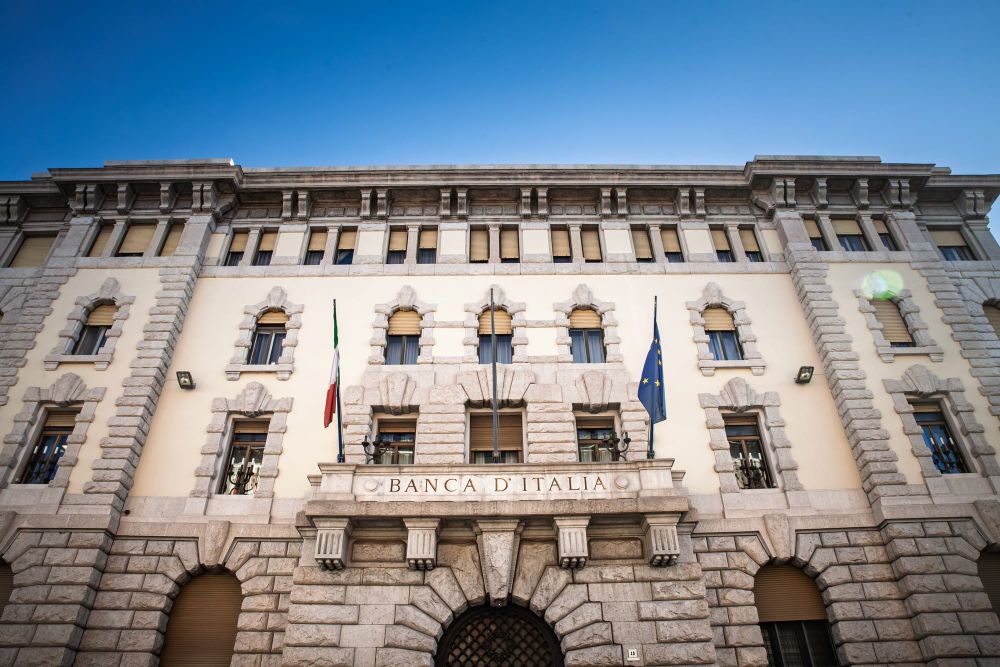
Banca d'Italia has imposed a €390,000 administrative fine on Olinda SAS, the French legal entity operating under the Qonto brand, for a series of anti-money laundering and suspicious transaction reporting failures. The penalty, the details of which were published in October 2025, follows an on-site inspection of Qonto's Italian operations conducted between January and April 2024, carried out pursuant to Legislative Decree 231/2007, Italy's primary legislative framework for AML and counter-terrorism financing compliance. The regulator characterised the failures as systemic and structural rather than episodic, a designation that elevates the seriousness of the enforcement action considerably.
Qonto is a Paris-based B2B neobank offering business accounts, payments, and expense management services to small and medium-sized enterprises across Europe. Its Italian operations brought the company within the supervisory remit of Banca d'Italia, which conducted the inspection to assess Qonto's compliance with Italian AML obligations applicable to payment service providers operating in the country. The inspection revealed multiple categories of deficiency that, taken together, indicated structural weaknesses in Qonto's compliance model rather than isolated procedural lapses.
SYSTEMIC FAILURES ACROSS MULTIPLE AML OBLIGATIONS
The violations identified by Banca d'Italia cover several foundational AML obligations. The regulator found deficiencies in client profiling, customer due diligence, and record-keeping — the trio of processes that underpin a financial institution's ability to assess, monitor, and document the risks posed by its customer base. Inadequate customer due diligence means that the institution may not have obtained sufficient information to understand the nature and purpose of customer relationships, while record-keeping failures can impair the ability of the institution and regulators to reconstruct transaction histories and customer activities when necessary.
In addition to those process-level failures, Banca d'Italia found that Qonto had failed to file suspicious transaction reports with the UIF, Italy's financial intelligence unit, in respect of operations that were potentially suspicious. The failure to report suspicious activity to the UIF is among the more serious categories of AML non-compliance, as it impairs the national intelligence-gathering capacity that law enforcement relies on to detect and investigate money laundering. Compounding the gravity of the findings, the regulator identified a failure in active cooperation with Italian authorities — a category of deficiency that speaks to the responsiveness and transparency of the institution in its dealings with supervisors, not merely its procedural compliance with technical rules.
NEOBANK REGULATORY SCRUTINY INTENSIFIES ACROSS EUROPE
The Banca d'Italia action against Olinda SAS reflects a growing pattern of regulatory enforcement directed at neobanks and fintech-native financial institutions operating across European borders. The EU's passporting regime allows a payment institution or electronic money institution authorised in one member state to offer services throughout the bloc, an arrangement that has enabled companies like Qonto to expand rapidly across multiple jurisdictions. Supervisors in host countries, however, are increasingly asserting their prerogative to inspect cross-border operators on-site and to apply national AML standards to foreign-licensed entities serving their markets.
For Qonto, the fine and its public disclosure carry both reputational and operational consequences. The company will need to present a credible remediation plan to Banca d'Italia demonstrating how each cited deficiency has been or will be addressed, and the characterisation of the failures as structural rather than incidental indicates that remediation must extend to the fundamental design of Qonto's compliance processes in Italy. The case is likely to intensify broader scrutiny of how neobanks operating across multiple European jurisdictions maintain consistent and adequate AML standards in each market they serve.