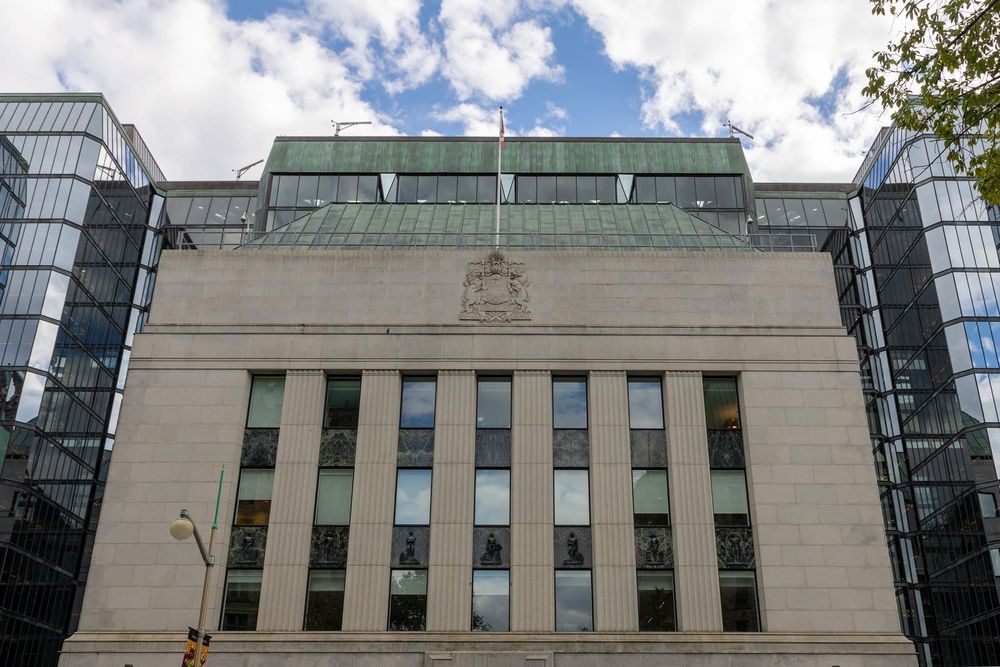
The Bank of Canada on Wednesday held its overnight rate target at 2.25%, extending the pause it began after cuts ended in October 2025 into a seventh consecutive meeting. The Bank Rate was maintained at 2.5% and the deposit rate at 2.20%, preserving the standard 25 basis point corridor around the policy target and keeping the bank's operating framework unchanged.
In its decision statement, the Governing Council said the data emerging since the previous meeting was largely in line with the projection contained in the July Monetary Policy Report, while flagging stronger upside risks to inflation that warranted continued caution. The combination signals a central bank comfortable with its current stance but alert to the risk that price pressures could re-emerge.
SEVENTH HOLD SINCE OCTOBER 2025
Wednesday's decision marks the seventh consecutive hold at 2.25% since the Bank of Canada concluded its cutting cycle in October 2025. The extended pause reflects a deliberate assessment by policymakers that the current stance of monetary policy is broadly appropriate for the economy's evolving inflation and growth trajectory, giving the bank time to observe the pass-through of earlier easing.
The 2.25% overnight target sits within the range that most Governing Council members regard as neutral, giving the bank flexibility to respond to shocks in either direction. The Bank Rate at 2.5% and deposit rate at 2.20% preserve the standard 25 basis point corridor around the target rate, ensuring the operating framework functions as intended and that market participants continue to see clear signals on the policy stance.
Governor Tiff Macklem and his colleagues have used the pause to assess how the earlier easing cycle is feeding through to activity and prices, while monitoring external developments including trade policy shifts and commodity price movements that can move Canadian inflation in short order. That watching brief has become a defining feature of the current phase of the rate cycle.
UPSIDE INFLATION RISKS FLAGGED
The Governing Council statement explicitly noted stronger upside risks to inflation, an incremental hawkish tilt relative to earlier communications. The Bank did not identify a single dominant driver in its brief release but pointed to the constellation of forces underpinning its cautious tone as it weighs the balance of risks around its central projection.
At the same time, the Committee said the incoming data was tracking largely in line with the July MPR forecast, indicating that the central projection has not shifted materially in the intervening period. That combination — a base case broadly on track, tempered by asymmetric upside inflation risks — supports the case for continued patience at 2.25% while preserving optionality on the direction of the next move.
For borrowers and market participants, Wednesday's decision means prime lending rates linked to the overnight target remain unchanged, and the trajectory of variable-rate mortgages and lines of credit continues to hinge on the outlook contained in the next Monetary Policy Report. Governing Council reiterated that it would continue to assess incoming data ahead of its next scheduled decision, keeping optionality open in both directions as the Committee monitors the balance of risks around inflation and growth.