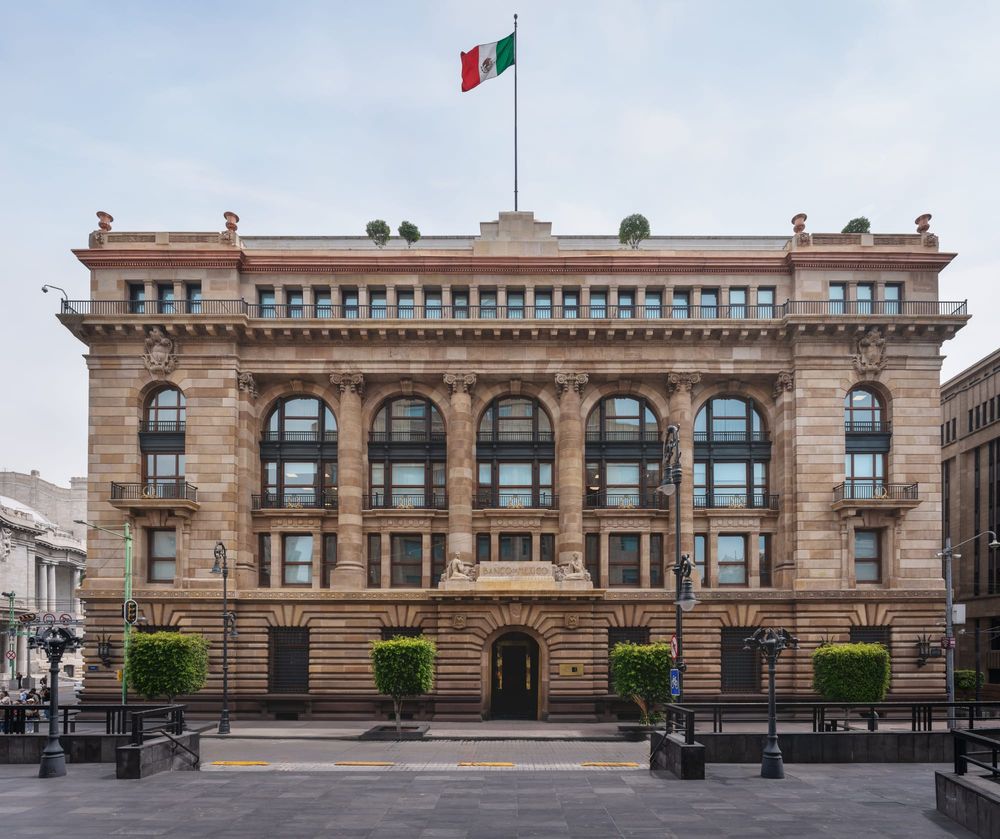
Banco de México held its overnight interbank target rate at 6.50% at its August meeting, a decision that was in line with market expectations and marked the second consecutive hold, the central bank said in its policy statement on 6 August 2026. The Governing Board also pushed back the expected timing of headline inflation's return to the 3% target.
End-2026 forecasts for both headline and core inflation were left unchanged at 3.5%, above the midpoint of the tolerance band around the 3% target. The board flagged that convergence of headline inflation to target has been delayed, a subtle but important qualifier that will inform market expectations for the pace of any future policy adjustments.
SECOND CONSECUTIVE PAUSE
Standing pat for a second meeting in a row consolidates a period of policy stability at Banxico after the extended easing cycle of the previous quarters. With the overnight rate at 6.50%, real ex-ante rates in Mexico remain firmly in restrictive territory relative to the central bank's own inflation forecasts, giving the Governing Board considerable room to observe the evolution of price dynamics before deciding on any next move.
Financial markets had broadly anticipated the outcome, and the central bank noted that the decision was in line with market expectations. That alignment limits the scope for a sharp reaction in the peso or in local rates markets on the back of the announcement itself, though attention is likely to shift towards the accompanying commentary and the quarterly report for any indication of how the delay in inflation convergence will feed into the reaction function.
Mexican real yields remain among the highest in the emerging-market complex, a feature that has continued to support portfolio flows into local bond markets even as some peers in Latin America have moved further along their easing cycles. Banxico's cautious approach reflects both the sensitivity of the currency to global rate differentials and the domestic experience of persistent services-sector price pressures.
INFLATION CONVERGENCE PUSHED BACK
The most notable element of the statement was the acknowledgement that headline inflation's convergence to target has been delayed, even as the numerical end-2026 forecast was held at 3.5%. That combination suggests the board sees the disinflation process as taking longer than previously projected without meaningfully changing its expected end point for the year, an unusual configuration that will need to be reconciled in the forthcoming quarterly analysis.
For monetary policy, a delay in convergence in the absence of a change in the numerical forecast typically points to a longer period of restrictive policy rather than to any imminent easing. It also signals continued vigilance around the second-round effects of past shocks, including services inflation and wage growth, both of which have been closely watched by Banxico officials.
By keeping both the policy rate and the numerical inflation forecast unchanged while extending the horizon over which the target is expected to be reached, Banxico has signalled a cautious stance. The full statement and quarterly context were published on the central bank's website, with a more detailed analysis due in the forthcoming quarterly inflation report.