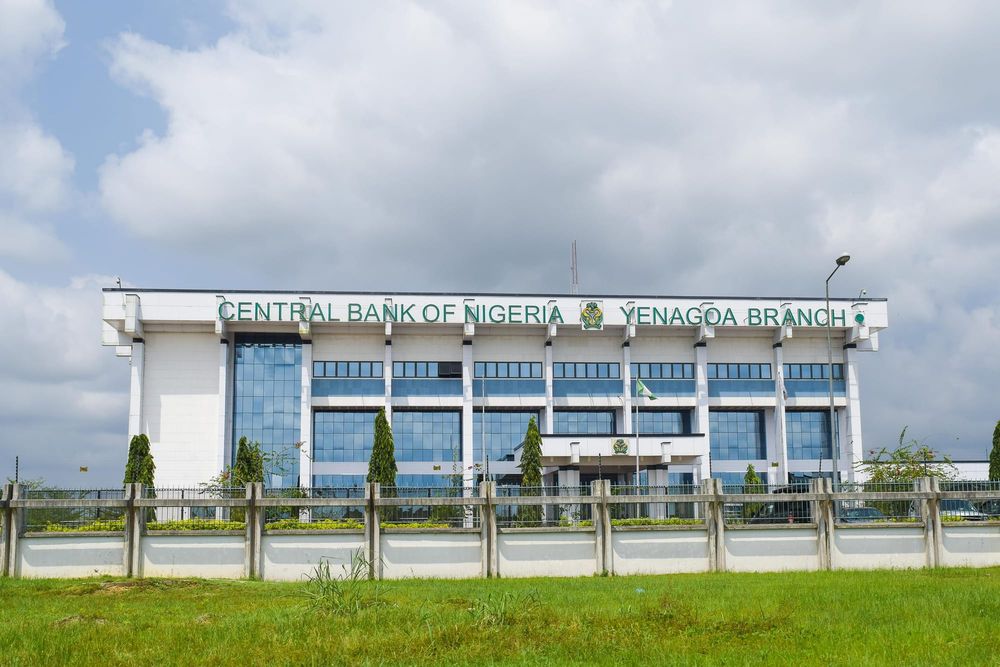
The Central Bank of Nigeria has formalised a dedicated ESG Compliance Department within its supervisory structure, giving it direct responsibility for overseeing environmental, social, and governance standards across all regulated banks and financial institutions in Nigeria. The move, taken in September 2025, marks the CBN's most concrete organisational step yet in embedding sustainability oversight into the core of its prudential supervision framework.
The new department will sit within the CBN's supervisory hierarchy and hold authority to assess, challenge, and where necessary penalise regulated institutions that fail to meet ESG compliance requirements. Its establishment transforms ESG supervision from a policy commitment into an operational reality, assigning clear accountability within the central bank for monitoring industry progress and enforcing standards consistently across the Nigerian banking sector.
BUILDING ON A YEAR OF REGULATORY ACTION
The creation of the ESG Compliance Department builds directly on the CBN's September 2024 Carbon Market Framework, which established Nigeria's regulatory approach to carbon credits, carbon market participation, and the role of financial institutions in channelling capital towards low-emission activities. That framework set expectations for how banks should engage with the country's nascent carbon market but stopped short of creating a dedicated enforcement mechanism. The new department fills that gap.
Alongside the CBN's own framework, the Financial Reporting Council of Nigeria has imposed a mandatory sustainability reporting mandate on large Nigerian companies, including banks, requiring them to publish standardised sustainability disclosures. The combination of the FRC's reporting requirement and the CBN's new compliance department creates a layered accountability structure: institutions must disclose their sustainability performance and a dedicated regulator will now assess whether those disclosures are accurate, complete, and improving over time.
For Nigerian banks, the formalisation of the ESG Compliance Department raises the stakes of sustainability commitments made in annual reports and investor presentations. Previously, ESG-related guidance from the CBN was treated by many institutions as aspirational rather than enforceable. The existence of a department with a specific supervisory mandate signals that the tolerance for cosmetic compliance — publishing sustainability reports that do not reflect genuine changes in lending practices or risk management — is diminishing.
SECTOR-WIDE IMPLICATIONS
Nigeria has the largest banking sector in sub-Saharan Africa by total assets, and the CBN's supervisory decisions carry influence well beyond its borders. The establishment of a dedicated ESG compliance function is likely to be noted by central banks elsewhere on the continent that are at earlier stages of developing their own sustainability supervision frameworks. It provides a model for how an African central bank can operationalise ESG oversight rather than leaving it as a policy aspiration embedded in speeches and guidelines.
The practical workload for Nigerian banks will intensify. Institutions will need to ensure that their sustainability data collection, internal controls, and disclosure processes are sufficiently robust to withstand examination by a regulator with specific expertise and authority in this area. Banks that have invested in ESG infrastructure are better positioned for this environment than those that have treated sustainability reporting as a communications exercise.
The CBN has not published detailed examination guidelines for the new department, but the combination of its carbon market framework and the FRC reporting mandate gives institutions a reasonable indication of the standards against which they will be assessed. Banks are expected to monitor further guidance closely and to engage proactively with the new department as it develops its supervisory programme in the months ahead.