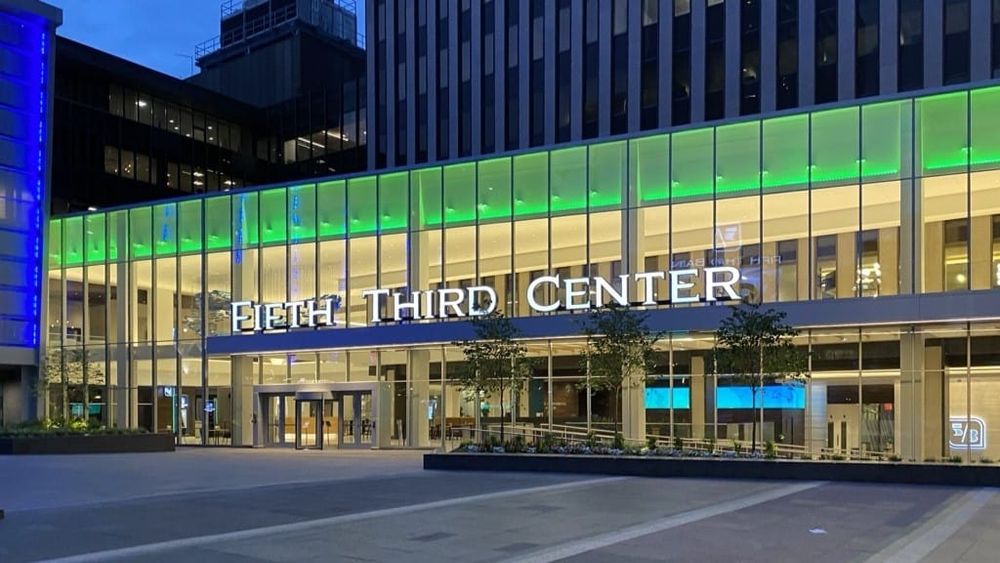
Fifth Third Bancorp has entered the integration phase of its acquisition of Comerica, bringing together two of the United States' prominent regional banking franchises into a combined institution with approximately $294 billion in total assets. The Cincinnati-based bank is now focused on deploying its digital and retail capabilities across Comerica's established footprint, with particular emphasis on the Texas markets where Comerica built a distinctive commercial banking presence over several decades and where economic growth has created significant banking demand in recent years.
The integration effort centres on Fifth Third's strategy of leveraging Comerica's middle-market commercial franchise, a segment that the acquiring bank has identified as central to the combined entity's revenue generation profile. Middle-market lending has historically been one of Comerica's most distinctive competitive strengths, particularly across Texas and California, and Fifth Third is now working systematically to align that client base with its own product range in areas spanning treasury management, commercial real estate finance, and corporate lending solutions.
DIGITAL AND RETAIL DEPLOYMENT IN TEXAS
Texas represents one of the most strategically significant elements of the Comerica acquisition, reflecting the state's economy attracting significant population inflows and corporate relocations in recent years, creating natural demand for banking services that a combined institution of greater scale is better placed to supply than either predecessor bank operating independently. Fifth Third plans to bring its consumer digital banking platform and retail banking disciplines into Comerica's Texas markets, seeking to build household penetration in cities where Comerica's brand was primarily associated with commercial rather than retail banking.
The digital integration component of the merger will require careful management of technology systems, customer communications, and staff alignment across the combined organisation. Retail and commercial clients on both sides of the transaction will be monitoring service continuity throughout the migration process, and Fifth Third has communicated a commitment to operational reliability during the integration period. Client attrition during system migrations has historically been among the most significant sources of value erosion in bank mergers, and managing this risk effectively will be an early test of the combined management team's execution capabilities.
The combined institution's footprint across the Midwest, Southeast, and key Sunbelt markets positions Fifth Third among the largest US regional banks, a tier that increasingly sits between the global systemically important institutions and the smaller community banks in terms of both product capability and regulatory treatment. Operating at the $294 billion asset level brings additional regulatory considerations alongside the strategic opportunities, including enhanced scrutiny from federal prudential supervisors on capital planning and stress testing.
FEE BUSINESSES AS A GROWTH LEVER
Beyond the traditional net interest income benefits of adding Comerica's loan and deposit book to its own, Fifth Third has identified fee-generating businesses as a primary target for growth within the combined franchise. Payments and wealth management are the two areas singled out by the bank as representing the most significant opportunities to scale fee revenue as a proportion of total income, reducing the combined institution's sensitivity to interest-rate fluctuations and providing more predictable earnings streams that institutional investors tend to value more highly than interest income.
Wealth management benefits from the scale that a combined, larger franchise brings, as broader client networks and larger asset bases support the economics of investment advisory, trust, and estate planning services. In payments, Fifth Third has made consistent investments in its capabilities over recent years, and the addition of Comerica's commercial client relationships creates cross-selling opportunities for treasury solutions, merchant processing, and corporate card services. The pace at which these revenue synergies are realised will be a primary benchmark by which analysts assess the strategic merit of the combination.