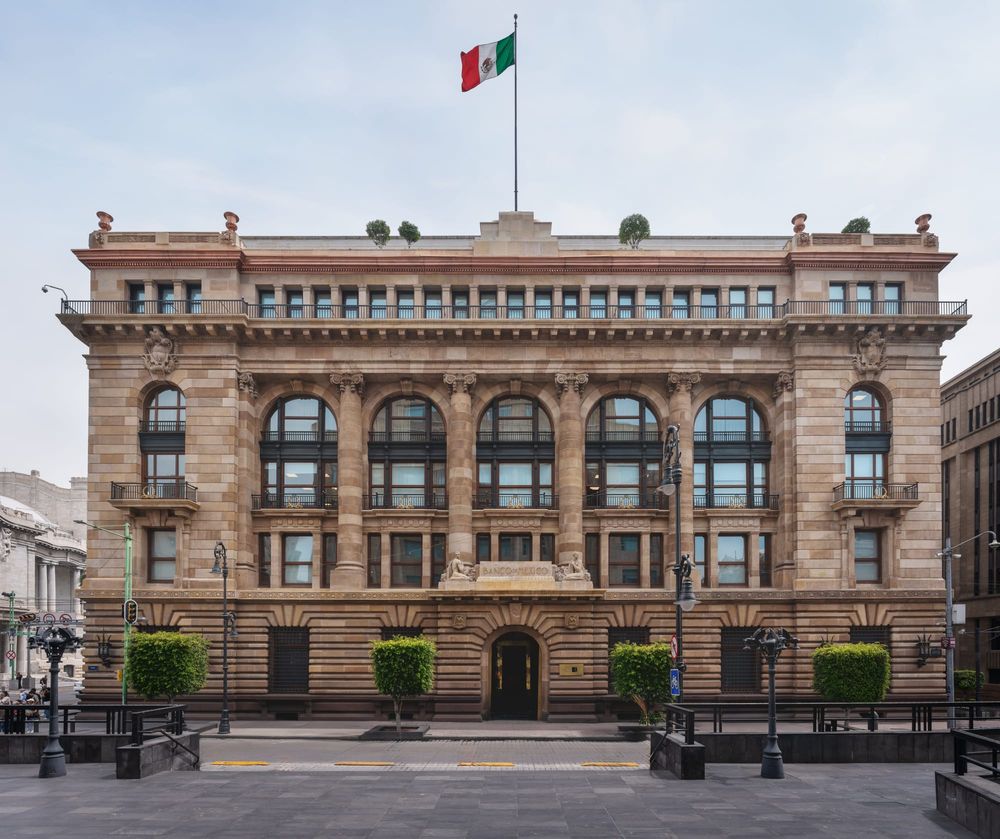
Mexico's central bank has approved a pivotal pilot for its digital peso, enlisting commercial banks in trials to explore wholesale and retail use cases for this central bank digital currency (CBDC). The program, approved by Banco de México (Banxico), signals Mexico's push into the digital finance era, aligning with global trends where over 130 countries are investigating similar technologies.
Banxico's work underscores the bank's commitment to CBDC development, first outlined in its 2020 fintech roadmap. The digital peso, envisioned as a digital liability of the central bank equivalent to physical cash, aims to enhance payment efficiency, financial inclusion, and monetary policy transmission. Participating banks include heavyweights such as BBVA México, Santander México, Citibanamex, Banorte, HSBC México, and Scotiabank Inverlat, representing a broad cross-section of Mexico's banking sector.
PILOT SCOPE AND TECHNICAL FOCUS
The trial will test interoperability between the CBDC platform and existing banking infrastructures. Wholesale applications will simulate large-value interbank settlements, potentially reducing settlement times via distributed ledger technology (DLT). Retail scenarios will examine peer-to-peer transfers, merchant payments, and programmable money features, such as automated remittances—a boon for Mexico's annual inflow from the U.S.
Banxico emphasizes privacy safeguards, ensuring the CBDC operates on a two-tier model where commercial banks handle end-user interactions, minimizing direct central bank exposure to retail data.
Technical parameters draw from Banxico's iterative experiments since 2021, including DLT proofs-of-concept. The current phase incorporates offline functionality for underserved regions, where many Mexicans remain unbanked. Banks will deploy sandbox environments to stress-test scalability.
BANKS' STRATEGIC COMMITMENT
BBVA México views the digital peso as an extension of its robust digital banking footprint. Santander México plans retail pilots integrating CBDC into its digital platforms.
Other participants like Banorte and HSBC bring specialized expertise: Banorte in remittances and HSBC in trade finance. The banks' involvement ensures the pilot's commercial realism.
GLOBAL CONTEXT AND RISKS
Mexico's move mirrors accelerated CBDC momentum worldwide. The Bahamas' Sand Dollar, launched in 2020, has achieved significant adoption, while China's e-CNY has processed billions of transactions. The European Central Bank's digital euro preparation phase and the U.S. Federal Reserve's exploratory work inform Banxico's cautious approach.
Challenges loom. Cybersecurity remains paramount; Banxico's framework mandates robust encryption. Financial stability risks, including bank disintermediation, prompt careful design. Governor Victoria Rodríguez Ceja has indicated the digital peso complements, not replaces, cash.
ECONOMIC IMPLICATIONS AHEAD
Success could benefit Mexico's economy. Remittances stand to gain from low-fee transfers, boosting rural economies. Wholesale efficiencies might reduce costs of interbank settlements. For banks, it's a defensive play against neobanks.
Regulators are monitoring illicit finance risks, integrating CBDC with Mexico's anti-money laundering regime. International interoperability trials are on the horizon. Banxico will refine its timeline based on pilot data, positioning Mexico as a CBDC leader in Latin America.
The digital peso pilot transcends technology—it's a blueprint for resilient, inclusive finance in an increasingly digital world. With banks driving execution, Mexico edges closer to an equitable digital future.