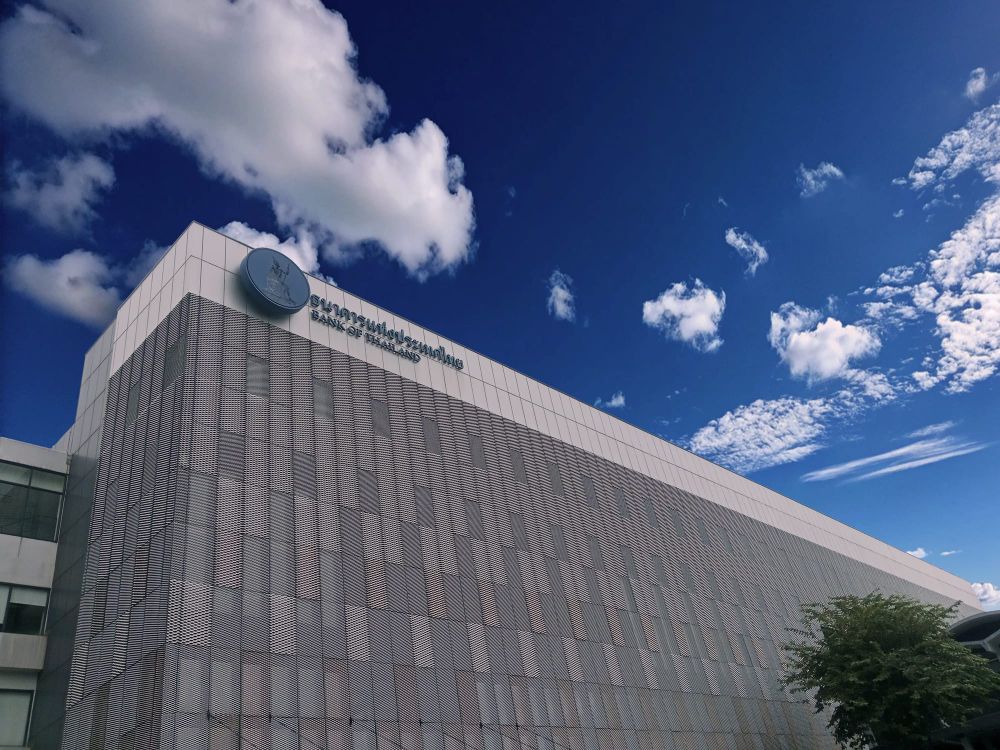
Vitai Ratanakorn formally assumed the governorship of the Bank of Thailand on 1 October 2025, beginning a five-year tenure at the helm of the country's central bank. The Thai cabinet had approved his appointment on 22 July 2025, ending a protracted search for a successor and setting the stage for a leadership transition that had attracted sustained attention from financial markets and domestic policymakers. His arrival at the central bank marks a significant shift in the institution's leadership profile after a prolonged period of uncertainty over the succession.
Vitai comes to the role from the Government Savings Bank, Thailand's state-owned retail savings institution, where he served as President. The move from a government bank presidency to the central bank governorship represents a shift in background from that of his predecessor, and market participants have been watching closely for early signals on the monetary policy direction Vitai and the Monetary Policy Committee intend to pursue, particularly given sustained government interest in lower borrowing costs.
A PROLONGED SUCCESSION PROCESS
The appointment of a new Bank of Thailand governor had been delayed for some months, and at one stage the central bank unexpectedly did not name a successor on the timeline that observers had anticipated. Reports at the time noted that the government and the central bank's board were navigating procedural requirements alongside, in some accounts, differing views on the appropriate candidate profile. The eventual cabinet approval of Vitai in July resolved the uncertainty that had hung over the institution during the interim period, providing clarity for the monetary policy calendar and for the bank's internal planning.
The Bank of Thailand occupies a central role in managing monetary policy, maintaining financial stability, and overseeing the country's foreign exchange reserves. Any change at the governor level is therefore scrutinised closely for its implications on interest rate decisions and broader macro-financial management. Vitai's background at the Government Savings Bank gives him direct exposure to government-sector finance and retail deposit markets, though the remit of the central bank is considerably broader and encompasses the full regulatory and monetary policy apparatus.
Vitai's first full monetary policy meeting as governor was scheduled for October 2025, placing him at the immediate centre of market expectations around the central bank's rate-setting decision. Financial institutions, corporate borrowers, and international investors will be watching the MPC's early decisions under his tenure for signals about whether his arrival marks any shift in the committee's approach to balancing the government's stated growth ambitions against the central bank's price stability mandate and its duty to preserve financial system resilience. The outcome of that meeting will provide the clearest early evidence of the direction Vitai intends to take the Bank of Thailand.
Under the terms of his appointment, Vitai will serve a fixed five-year term as governor of the Bank of Thailand, a tenure structure that is standard for the position and designed to support institutional independence and policy continuity across political cycles. The fixed duration also means that the framework within which successor decisions are made is clearly established, reducing the scope for governance uncertainty of the kind that characterised the succession process preceding his own appointment.
Vitai's first full monetary policy meeting as governor was scheduled for October 2025, placing him at the immediate centre of market expectations around the central bank's rate-setting decision. Financial institutions, corporate borrowers, and international investors will be watching the MPC's early decisions under his tenure for signals about whether his leadership marks a shift in the committee's approach to balancing the government's growth ambitions against the central bank's price stability mandate and its duty to maintain financial system resilience.