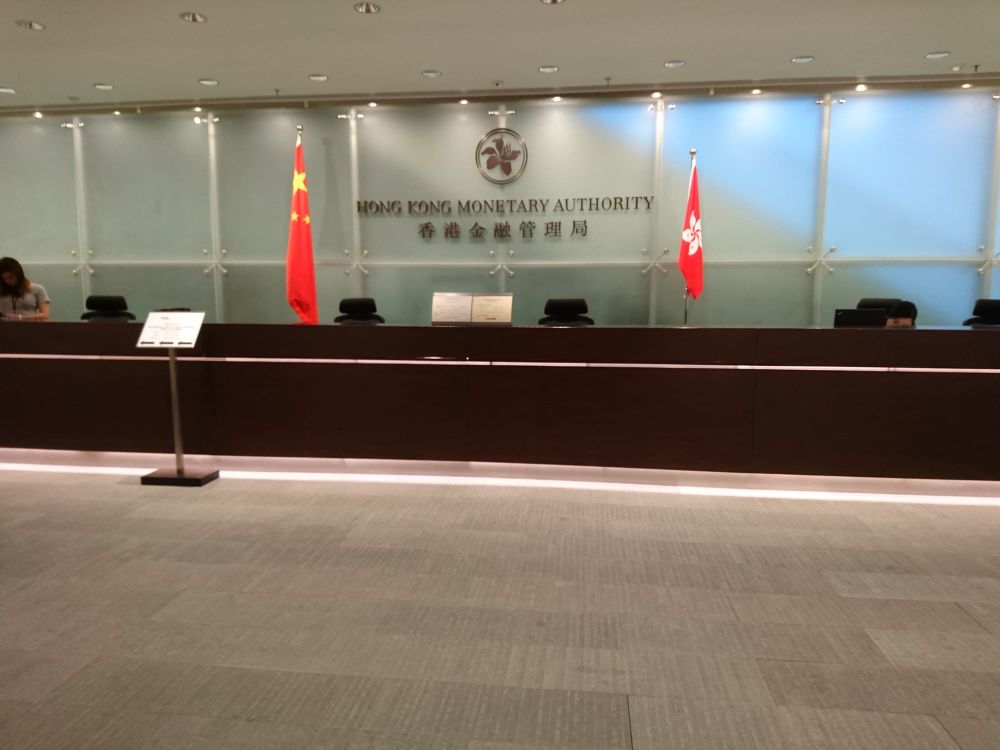
The Hong Kong Monetary Authority (HKMA) said that banks had implemented the requirements of its circular on mainland Chinese customers' investment accounts, and that mainland customers could still open accounts in the city.
"The banking industry has implemented the new regulatory requirements set out in the HKMA circular to ensure the account opening process is compliant and orderly," the HKMA said. "Chinese mainland customers continue to apply for opening accounts, and in general, the account opening process has been operating smoothly." The authority said the new measures would enhance Hong Kong's advantages as an international financial centre.
THE MAY CIRCULAR
The HKMA issued a circular to banks in late May, applying to banks requirements similar to those already imposed on brokers for managing mainland Chinese customers' accounts. Banks must require mainland clients opening investment accounts to declare that their investment funds come from sources outside mainland China.
Banks must also close investment accounts that were opened with questionable or forged documents. CROSS-BORDER CRACKDOWN
The rules followed a crackdown by the China Securities Regulatory Commission on illegal cross-border brokerage, which also targeted Longbridge Securities. In May the CSRC imposed penalties of about RMB411 million on subsidiaries of Tiger Brokers' parent UP Fintech and proposed penalties of about RMB1.85 billion on Futu entities, for conducting securities business in mainland China without licences. Some mainland residents had reported rejected applications for Hong Kong bank accounts as institutions tightened account-opening policies. The scrutiny comes as China tightens controls on cross-border investment.