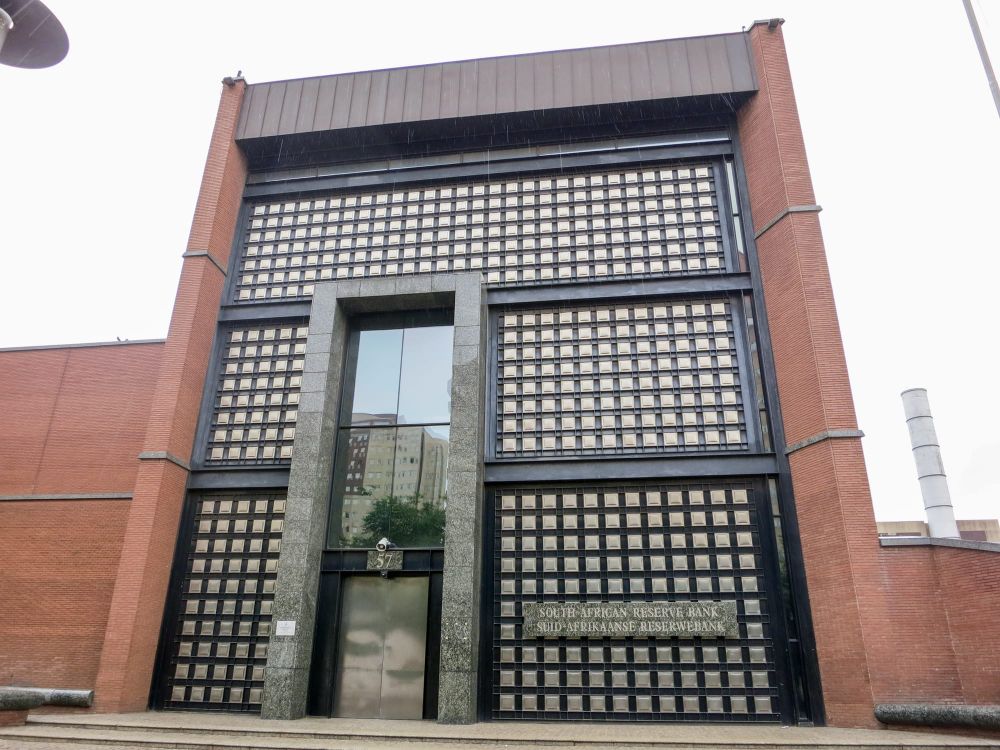
The South African Reserve Bank's Monetary Policy Committee voted to hold the repo rate at 6.75 per cent at its January 2026 meeting, pausing an easing cycle that had delivered a cumulative reduction of 150 basis points since September 2024. The decision reflects the committee's assessment that, while the domestic inflation outlook remains broadly manageable and the economy has benefited from the rate reductions already delivered, external risks — in particular the potential for energy price volatility associated with ongoing tensions in the Middle East — warrant a period of caution before any further monetary accommodation is considered.
The hold brings to a temporary halt a sequence of cuts that began in the second half of 2024, when South African inflation moved closer to the midpoint of the Reserve Bank's 3 per cent to 6 per cent target band and the committee judged that conditions were sufficiently favourable to begin unwinding a portion of the restrictive stance it had maintained during the preceding tightening phase. That easing phase provided some relief to South African consumers and businesses operating under significant financial pressure, though borrowing rates across the country's commercial banking sector remained elevated in absolute terms relative to the conditions that prevailed prior to the global tightening cycle.
MIDDLE EAST RISKS CLOUD INFLATION OUTLOOK
The Monetary Policy Committee specifically identified energy price risks stemming from the Middle East as a factor weighing on the inflation outlook in its January assessment. South Africa is a significant net importer of crude oil, meaning that movements in international energy prices feed relatively directly into domestic fuel costs and, through transport, logistics, and distribution channels, into the broader consumer price index over subsequent months. Any sustained escalation in oil prices attributable to geopolitical disruption or supply constraint in the Middle East would complicate the Reserve Bank's ability to continue easing without risking a rebound in inflation that could push the headline rate toward or above the upper limit of the target band.
The committee's decision to hold rather than cut further was consistent with a broader pattern observable across emerging-market central banks at the start of 2026, where a combination of residual dollar strength, uncertain global growth trajectories, and the persistence of geopolitical uncertainty in energy-producing regions had prompted policymakers to moderate the pace of monetary easing, even where the domestic inflation environment might otherwise have been permissive of additional cuts. The SARB's approach of pausing to assess the external risk landscape before proceeding is characteristic of a central bank seeking to preserve the credibility it rebuilt through its earlier tightening cycle.
BANKING SECTOR AND GROWTH IMPLICATIONS
For South African banks and their clients, the rate hold has mixed implications. Higher-for-longer borrowing costs continue to weigh on consumer spending and business investment in an economy where growth has underperformed potential for an extended period and where household balance sheets carry significant levels of debt accumulated during years of low rates followed by the shock of rapid tightening. The South African banking sector entered 2026 managing elevated credit impairments and non-performing loan ratios, and further rate relief would have provided some improvement in debt-servicing capacity for stressed borrowers.
At the same time, the Reserve Bank's cautious approach is designed to underpin confidence in the rand and in South Africa's inflation-targeting framework, objectives that carry long-term value for the financial system even when they constrain the pace of near-term easing. The committee's statement made clear that it would continue to monitor incoming inflation data, the evolution of global energy markets, and the broader external risk environment, signalling that additional cuts remained within the range of possible outcomes but that their timing would depend on how conditions developed in the period ahead.