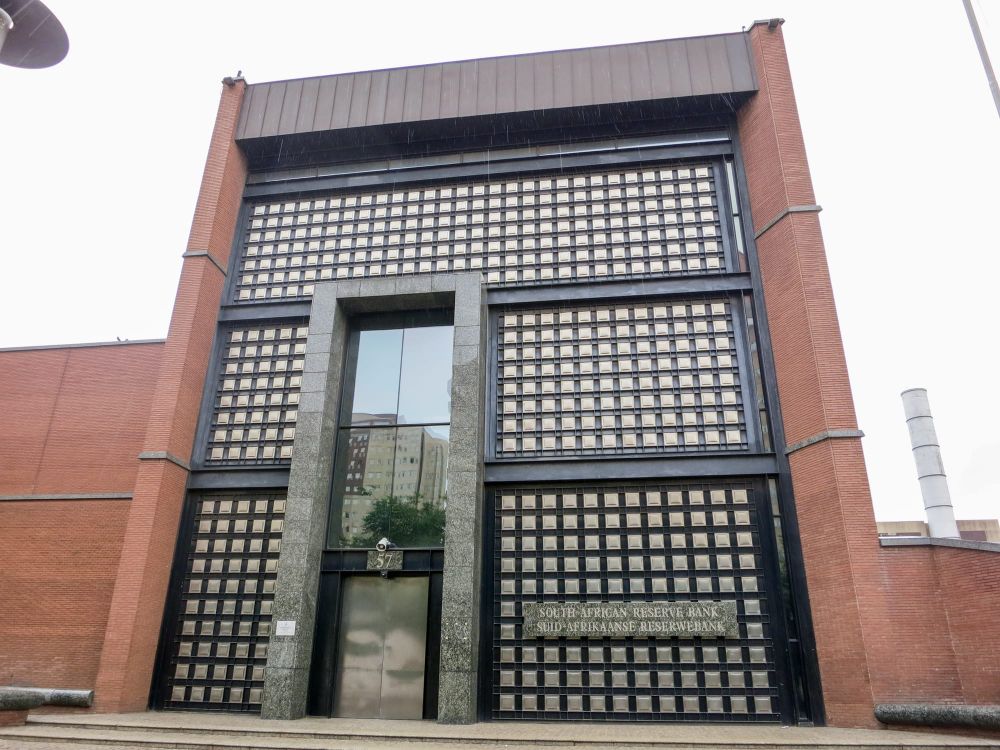
The South African Reserve Bank cut its benchmark repo rate by 25 basis points to 6.75% on 20 November 2025, extending an easing cycle that has now delivered six consecutive reductions since it began in September 2024. The decision brings the prime lending rate down to 10.25%, offering further relief to households and businesses carrying variable-rate debt at a time when the economy continues to navigate a complex operating environment.
The Monetary Policy Committee cited a downside surprise on inflation as a principal factor behind the latest move. Consumer price pressures in South Africa had moderated more quickly than the Committee's prior forecasts had envisaged, creating space for continued policy accommodation without endangering the bank's price-stability mandate. The SARB published the decision in a statement on its website following the conclusion of the two-day MPC meeting.
EASING CYCLE REACHES SIXTH MOVE
Six cuts across just over a year represents a substantial recalibration of monetary conditions in South Africa. The cycle began as global commodity prices eased and domestic demand remained subdued, allowing the Committee to gradually unwind some of the tightening that had been put in place to contain post-pandemic inflation. Each move has been measured at 25 basis points, reflecting a deliberate, step-by-step approach rather than a front-loaded response, and the November decision continues that pattern.
The reduction in the prime lending rate to 10.25% is particularly significant for mortgage holders and small businesses, whose borrowing costs are typically linked directly to prime. For a substantial portion of South African borrowers, each quarter-point reduction translates into modest but tangible savings on monthly repayments, supporting consumer spending at a time when the broader economy continues to navigate structural constraints including energy supply and logistics challenges that have weighed on growth for several years.
The SARB's communication ahead of the November meeting had prepared markets for the possibility of further easing, with analysts broadly anticipating a 25 basis-point move. The bank has consistently emphasised data-dependency in its guidance, and the latest inflation data gave the Committee the confidence it needed to proceed with another reduction rather than holding rates unchanged.
INFLATION SURPRISE DRIVES DECISION
The Committee's statement pointed to a downside inflation surprise as the key trigger for the November decision. South Africa's consumer price index had come in below expectations in the most recent readings, reflecting lower fuel prices and contained food inflation. The SARB monitors a range of measures, including core inflation that strips out volatile food and energy components, and the trend across those measures was judged to be consistent with a continued accommodative stance.
Looking ahead, the Committee noted it would continue to assess the balance of risks to both the inflation outlook and economic growth. The rand's performance against major currencies and the path of global interest rates — particularly decisions by the United States Federal Reserve — remain important variables that the SARB must weigh alongside domestic conditions. With the prime rate now at 10.25%, South Africa's monetary policy settings are materially less restrictive than at the peak of the tightening cycle, though the bank has made clear that further moves will depend on incoming data rather than a pre-set schedule.